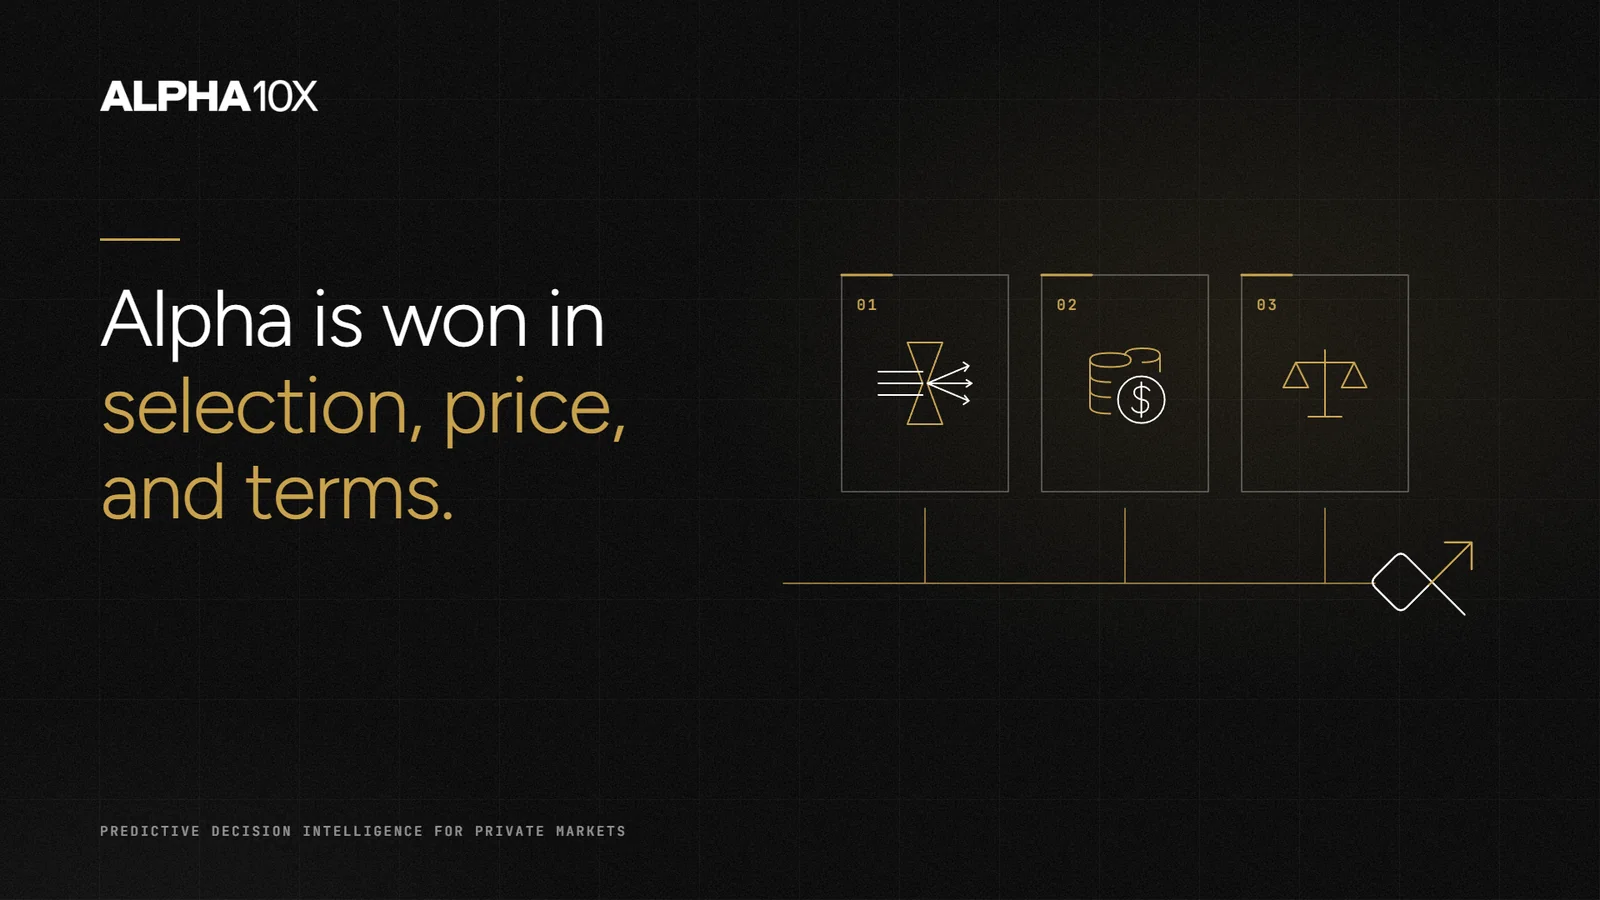
Alpha is won in selection, price, and terms
Public assets are marked to market. Private assets are marked to model between liquidity events.
Public assets are marked to market. Private assets are marked to model between liquidity events. Prices are negotiated, and the investment thesis may take years to prove itself.
Alpha is won in selection, price, and terms.
Alpha—the return above a benchmark after adjusting for risk—begins with deciding which companies to back, what to pay, and on what terms. Operational execution matters throughout ownership, but the entry decision establishes the economics against which it must deliver.
Underwriting can imply false precision
A precise valuation does not make the judgment behind it sound.
Private-market underwriting remains largely manual. A small group interprets incomplete evidence and decides whether a deal clears the firm’s return threshold. Assumptions are implicit, reasoning is unstructured, and investment logic remains locked in people, spreadsheets, and static documents.
Even rigorous teams can struggle to reconstruct which assumptions justified the price, what evidence was available, and what subsequent performance taught them. Confidence in management, prevailing sentiment, or an influential deal sponsor can outweigh the evidence.
By the time the thesis is tested, the capital is committed. Without a reliable record of the original reasoning, experience does not consistently become institutional learning.
The margin for error is shrinking
Bain & Company projects private-market assets under management will reach $60–65 trillion by 2032. As capital scales, the ability to distinguish opportunity from risk—and maintain discipline on price and terms—becomes increasingly consequential.
The pressure shows in deal economics. Before 2012, carve-outs generated approximately 3.0x MOIC, compared with 1.8x for buyouts overall. Since 2012, average carve-out returns have fallen to 1.5x, slightly below broader buyout performance. Bain attributes the deterioration to higher acquisition prices and weaker operational improvements.
Duration compounds the problem. A 1.5x multiple realized over ten years equates to approximately 4.1% annually before fees and inflation. A positive multiple alone does not establish adequate compensation for risk and years of illiquidity.
Outcomes also vary sharply by manager. The cited J.P. Morgan Asset Management comparison puts the gap between top- and bottom-quartile private equity managers at approximately 19 percentage points, versus approximately 3 for large-cap public equity.*
The opportunity is substantial. So is the cost of weak selection, mispricing, and inadequate terms.
Access alone risks industrializing beta
Access still matters, particularly for proprietary opportunities. But sourcing alone does not determine returns.
Data platforms have broadened access to information, and general-purpose AI has sharply reduced the cost of research and analysis. These tools improve productivity. Private markets, however, operate on long investment cycles: faster analysis creates value only if it informs better capital allocation.
The unmet need is predictive Decision Intelligence: estimating investment outcomes, quantifying uncertainty, and determining which deals, prices, and terms satisfy return objectives and mandate constraints before capital is committed.
Without that discipline, scale risks industrializing beta—returns driven by market exposure—without establishing a repeatable source of alpha.
Strengthen the decision before committee
ALPHA10X brings quantitative discipline to private-market underwriting. Prediction is its north star; Decision Intelligence is its product.
The ALPHAcodex connects evidence, assumptions, and constraints in explicit, auditable investment logic. Deal teams can trace claims to sources, test the seller’s narrative against independent evidence, assess mandate fit, and surface contradictions, risks, and information gaps before terms are agreed.
Its predictive layer combines machine learning with Bayesian inference to estimate the probability of outperformance and update that assessment as new evidence emerges. It identifies return drivers, assesses downside, and tests how entry price, transaction terms, and operating assumptions affect expected returns.
The partner can then proceed, reprice, renegotiate, or pass—with a clear account of what supports the decision and what would change it. Investors retain the final say.
Make each investment improve the next
The investment case becomes a record the firm can test against actual performance. As outcomes emerge, original assumptions can be revisited, predictive models calibrated, and lessons applied across subsequent deals.
Individual judgment becomes an institutional asset. The advantage compounds through a growing understanding of which decisions succeed, which fail, and why.
ALPHA10X targets more than 400 basis points of gross IRR uplift through better selection, pricing, and terms—a management objective, rather than a demonstrated performance result.
Alpha is won in selection, price, and terms. Walk into committee knowing what must be true, what the evidence supports, and what would change the decision.
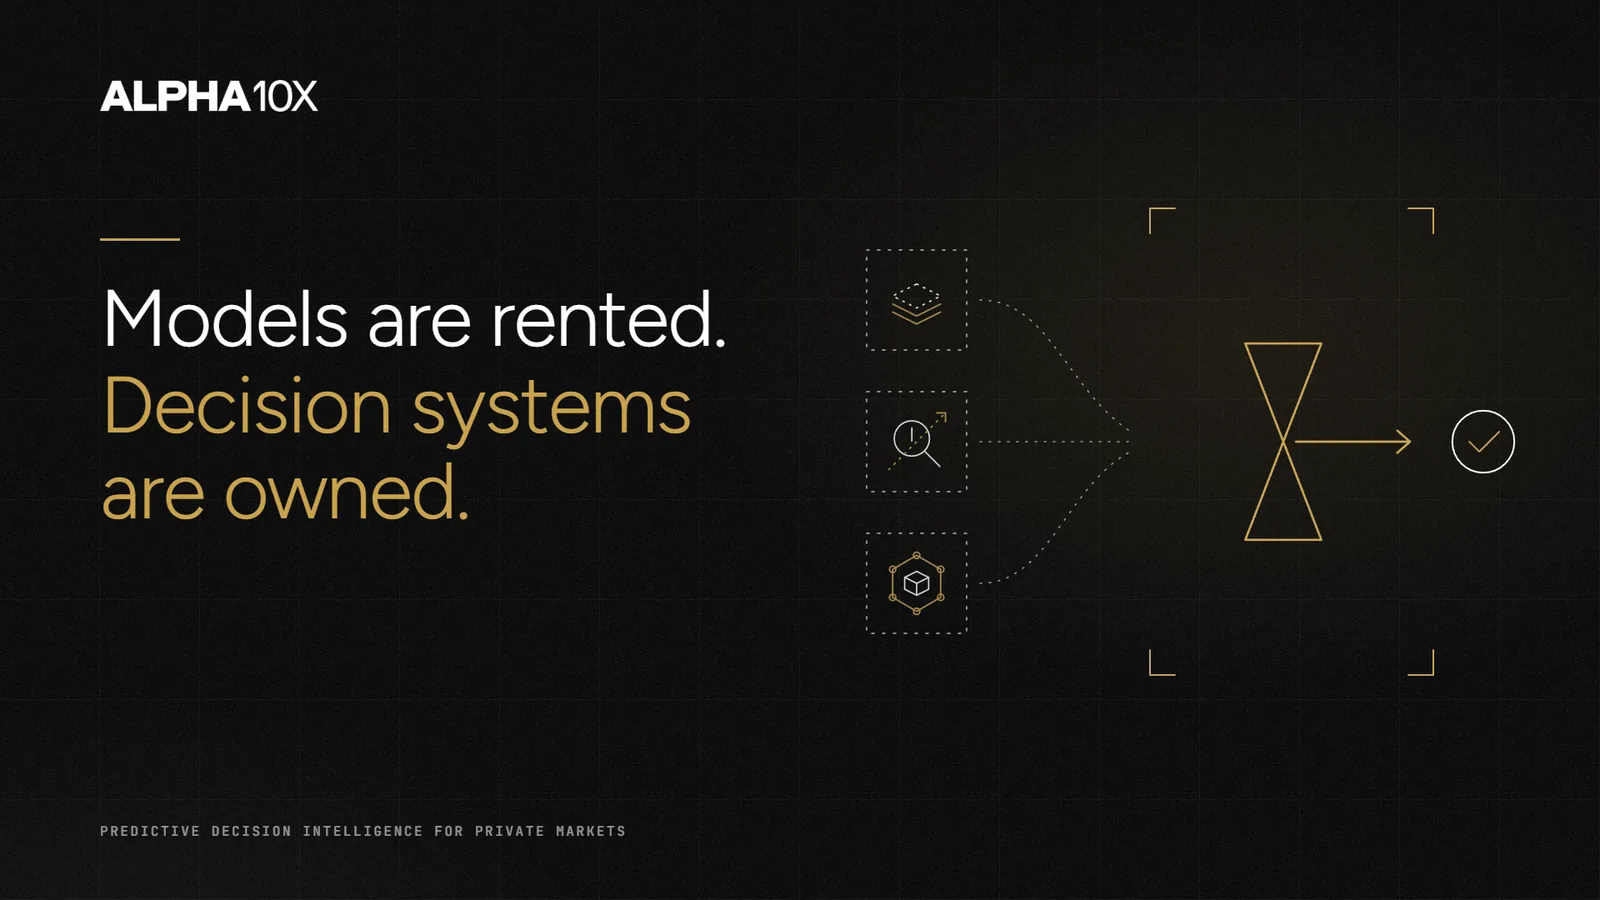
The investment record is yours.
Capital is abundant. Superior judgment is scarce.
Blog
Why Doha. Why now. What’s next?
Why Doha? Global capital, strong partnerships, and a commitment to innovation under Qatar National Vision 2030.
Blog
Twenty Years of Ups and Downs in the Venture Capital Market
A long view of the venture capital market that finances innovation, and the cycles it has gone through.
 Founder & Group CEO